In Simple Words
Imagine buying a weather policy based on a thermometer installed at an airport 20 miles away. If a severe drought hits your specific farm but the airport station records adequate rainfall, you receive zero compensation despite losing your entire harvest. This mismatch between actual farm loss and index payout reduces farmers' willingness to pay for insurance unless the contract is heavily subsidized.
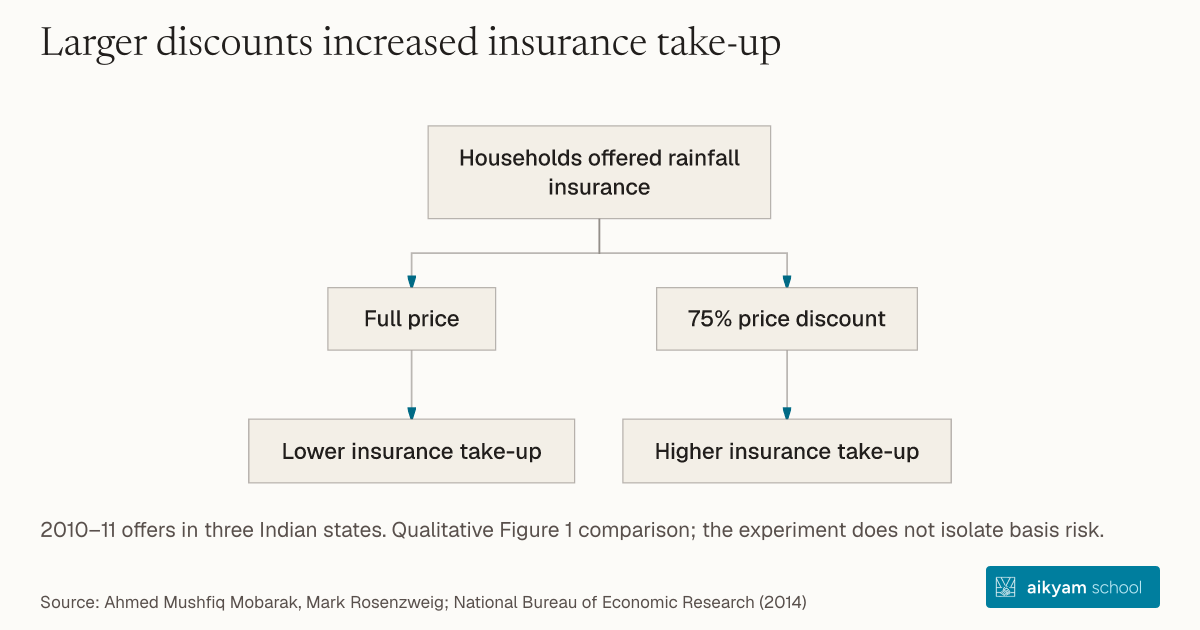
Households offered rainfall insurance
- Full price
- Lower insurance take-up
- 75% price discount
- Higher insurance take-up
2010–11 offers in three Indian states. Qualitative Figure 1 comparison; the experiment does not isolate basis risk.
See source →Research question
Weather index insurance payout triggers are tied to distant weather stations rather than actual on-farm crop damage, creating basis risk where farmers suffer crop losses without receiving an insurance payout.
Participants
N = 5,263 rural households across 42 villages in three Indian states evaluated across varying distance radii from reference weather stations.
Study Design
Econometric estimation of insurance demand elasticities across price discount tiers (10%, 50%, 75% subsidies) and spatial distance to reference weather stations.
Results
Unsubsidized insurance take-up is low (below 15%), but demand increases significantly to 60.2% when price subsidies reach 75%, demonstrating that spatial basis risk severely dampens demand at actuarially fair prices.
Takeaway
Deploy localized micro-weather sensor networks or satellite-derived precipitation indexes to minimize spatial basis risk and increase voluntary insurance adoption.