In Simple Words
Imagine offering people insurance on an airplane flight. Buyers are willing to pay $10 more if the policy promises to give them a tiny snack voucher whenever the flight is delayed by 10 minutes, but they only offer $10 more for a policy that pays $10,000 if the plane crashes. They react strongly to small, frequent perks they can picture easily, but fail to properly calculate the massive value of protection against rare catastrophic loss.
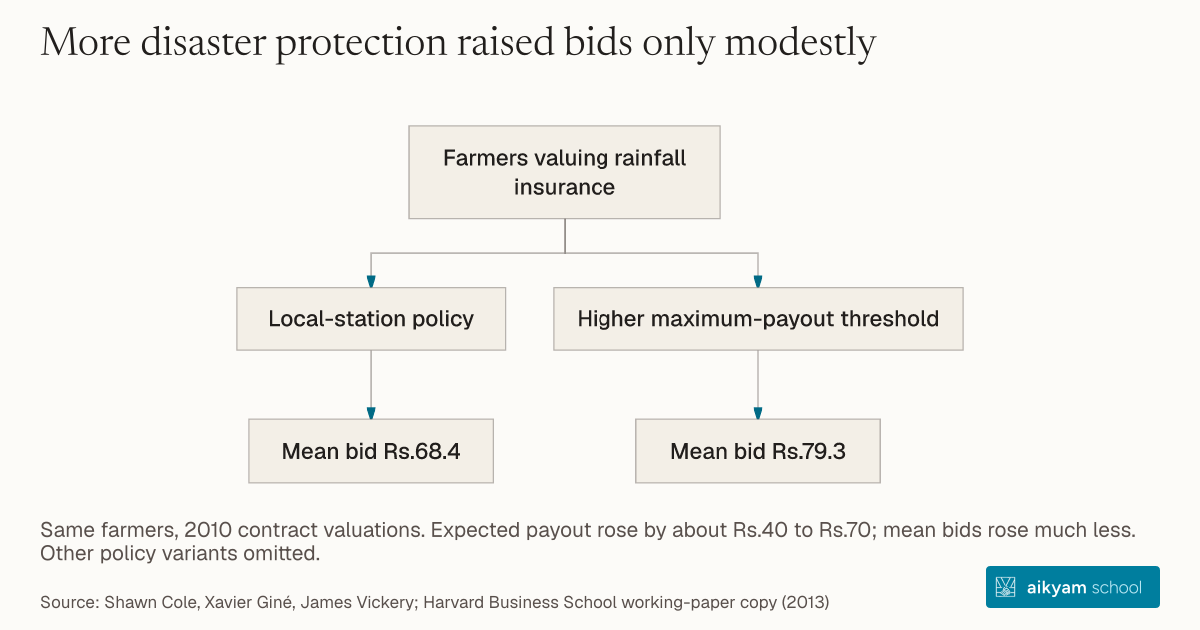
Farmers valuing rainfall insurance
- Local-station policy
- Mean bid Rs.68.4
- Higher maximum-payout threshold
- Mean bid Rs.79.3
Same farmers, 2010 contract valuations. Expected payout rose by about Rs.40 to Rs.70; mean bids rose much less. Other policy variants omitted.
See source →Research question
Standard microinsurance design assumes consumers hold rational expectations and correctly evaluate variations in financial contract terms. However, boundedly rational agricultural producers often misjudge the actuarial impact of structural contract changes, overvaluing minor payout tweaks while undervaluing major catastrophic coverage shifts.
Participants
N = 1,978 smallholder farmers (1,464 existing study participants and 514 new participants) across rural Andhra Pradesh, India.
Study Design
In-field incentive-compatible Becker-DeGroot-Marschak (BDM) mechanism eliciting real monetary willingness-to-pay across 4 distinct insurance contract variations (Real Policy, Modified Exit, Modified mm Payment, and Basis Risk).
Results
Mean willingness-to-pay for the real policy was Rs. 68.4 (median Rs. 70). Modifying the exit threshold increased expected payout value by Rs. 40-70 but only increased willingness-to-pay by Rs. 10.86 (p < 0.01); reducing per-mm shortfall payouts reduced expected value by Rs. 10-20 and reduced willingness-to-pay by Rs. 11.90 (p < 0.01). Introducing basis risk (distant station) halved valuation, reducing bids by Rs. 29.45 (p < 0.01).
Takeaway
Regulate private microinsurance contract structures to prevent insurers from exploiting consumer behavioral biases through high-frequency, low-value policy tweaks that under-protect against severe tail events.
Source and citation
See source →Read alongside the research
Plain-English glossary
Original explanations, informed by the references below. Examples are illustrations, not data from the studies above. The research text stays unchanged.
- Median
The middle number after arranging the values from smallest to largest. If there are two middle numbers, use their average.
ExampleFor the values 2, 4 and 12, the middle value is 4. The median is 4.
NIST · Measures of location ↗Read more about median →