In Simple Words
A strict school that punishes any mistake gets 100% pass rates, but students never attempt difficult math problems. A subsidized school that allows mistakes accepts a 15% failure rate on tough exams but produces far more capable engineers. Government loan guarantees act like a safety net for lenders, allowing them to tolerate business failures so entrepreneurs can take bold risks that grow the economy.
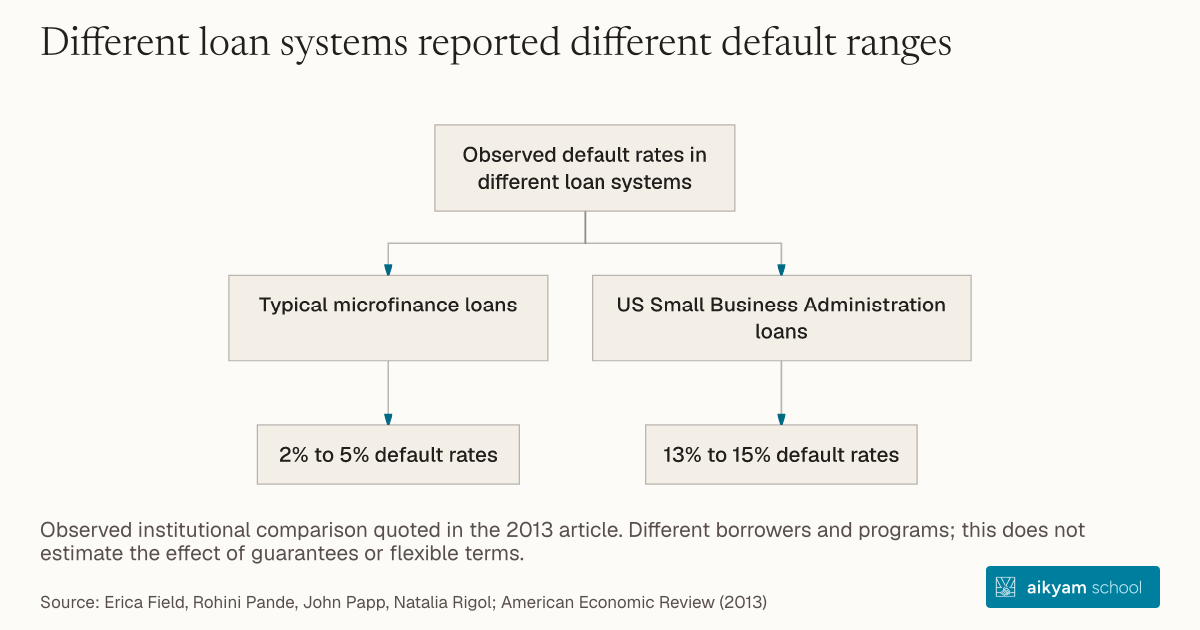
Observed default rates in different loan systems
- Typical microfinance loans
- 2% to 5% default rates
- US Small Business Administration loans
- 13% to 15% default rates
Observed institutional comparison quoted in the 2013 article. Different borrowers and programs; this does not estimate the effect of guarantees or flexible terms.
See source →Research question
Microfinance institutions in developing countries enforce near-zero default rates (2%–5%) through rigid contracts, suppressing business growth, whereas developed-country small business credit programs use government subsidies to tolerate higher default rates in exchange for flexible debt structure.
Participants
Comparative institutional analysis of U.S. Small Business Administration (SBA) loan portfolios versus microfinance client pools in developing nations.
Study Design
Observational policy comparison of subsidized small business lending structures, repayment grace periods, and institutional default tolerance.
Results
U.S. SBA small business loans offer flexible terms (including delayed initial payments up to 3 months) and tolerate default rates of 13% to 15% (compared to 2% to 5% for typical microfinance institutions) supported by public guarantees.
Takeaway
Implement government credit guarantees for small business lenders to absorb default risk premiums and unlock flexible loan terms for high-growth micro-entrepreneurs.