In Simple Words
Imagine two shoppers looking at a car warranty. An average driver notices the contract changed but doesn't calculate the math, whereas a trained mechanic calculates the exact cost of replacing an engine versus fixing a dent and adjusts their bid sharply based on true repair costs.
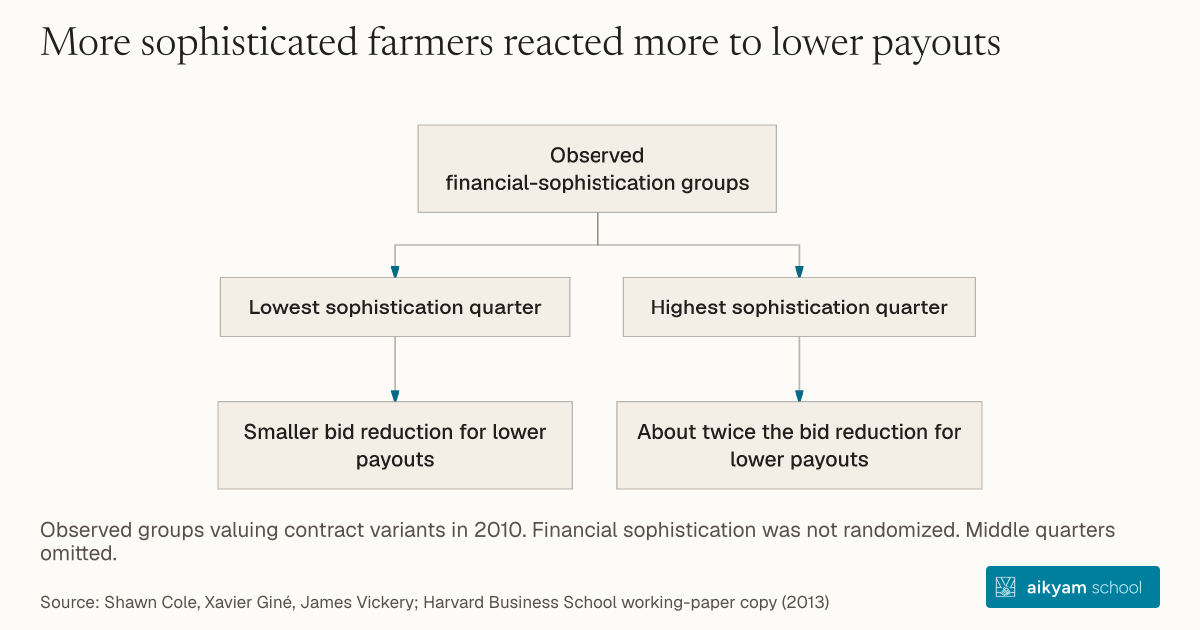
Observed financial-sophistication groups
- Lowest sophistication quarter
- Smaller bid reduction for lower payouts
- Highest sophistication quarter
- About twice the bid reduction for lower payouts
Observed groups valuing contract variants in 2010. Financial sophistication was not randomized. Middle quarters omitted.
See source →Research question
Unsophisticated consumers often fail to adjust their valuations appropriately when complex financial contracts are modified, creating opportunities for mispricing and sub-optimal insurance coverage.
Participants
N = 1,978 farmers in Andhra Pradesh, India.
Study Design
Becker-DeGroot-Marschak (BDM) mechanism interacting a self-reported 3-item financial sophistication index with contract term modifications.
Results
Moving from the least to the most financially sophisticated quartile roughly doubled the reduction in willingness to pay for reduced payout per mm (-11.90 Rs baseline) and increased willingness to pay for a higher exit threshold (+10.86 Rs baseline) by 50%.
Takeaway
Assess consumer financial sophistication before introducing complex parametric insurance products, pairing sales with decision-support tools for low-sophistication clients.