In Simple Words
Think of two buyers examining a smartphone warranty. An experienced technician reads the exact fine print to see if battery replacement is covered and pays extra for it, while an inexperienced buyer pays the same price for a shiny logo regardless of whether the battery is covered.
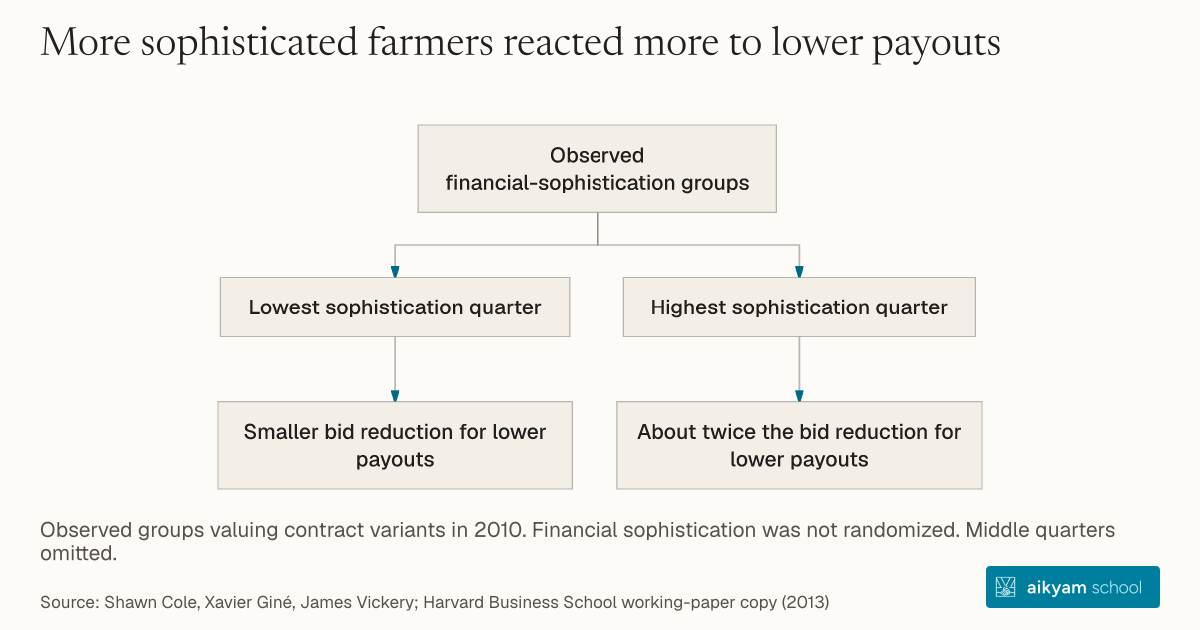
Observed financial-sophistication groups
- Lowest sophistication quarter
- Smaller bid reduction for lower payouts
- Highest sophistication quarter
- About twice the bid reduction for lower payouts
Observed groups valuing contract variants in 2010. Financial sophistication was not randomized. Middle quarters omitted.
See source →Research question
Standard financial models assume consumers evaluate insurance terms rationally, but varying financial literacy causes less sophisticated consumers to misprice subtle contract modifications and undervalue key protection features.
Participants
N = 1,978 smallholder farmers across Mahbubnagar and Anantapur districts, Andhra Pradesh, India.
Study Design
Incentive-compatible Becker-DeGroot-Marschak (BDM) mechanism evaluating willingness-to-pay across financial sophistication quartiles.
Results
Moving from the lowest to highest quartile of financial sophistication roughly doubles the reduction in willingness-to-pay for reduced millimeter deviation payments (-Rs. 1.688 per quartile tier, p < 0.01), increases willingness-to-pay by 50% for policies with higher exit thresholds (+Rs. 1.116 per quartile tier, p < 0.01), and quadruples sensitivity to basis risk (-Rs. 4.007 per quartile tier, p < 0.01).
Takeaway
Assess consumer financial sophistication prior to launching microinsurance products to ensure target populations accurately comprehend and value key risk-hedging clauses.