In Simple Words
Imagine a job applicant whose resume shows degrees and test scores, but whose former coworkers know their real-world problem-solving ability under pressure. While reading a resume gives a basic baseline score, combining resume credentials with peer recommendations gives a complete, 360-degree picture that identifies the absolute top performers.
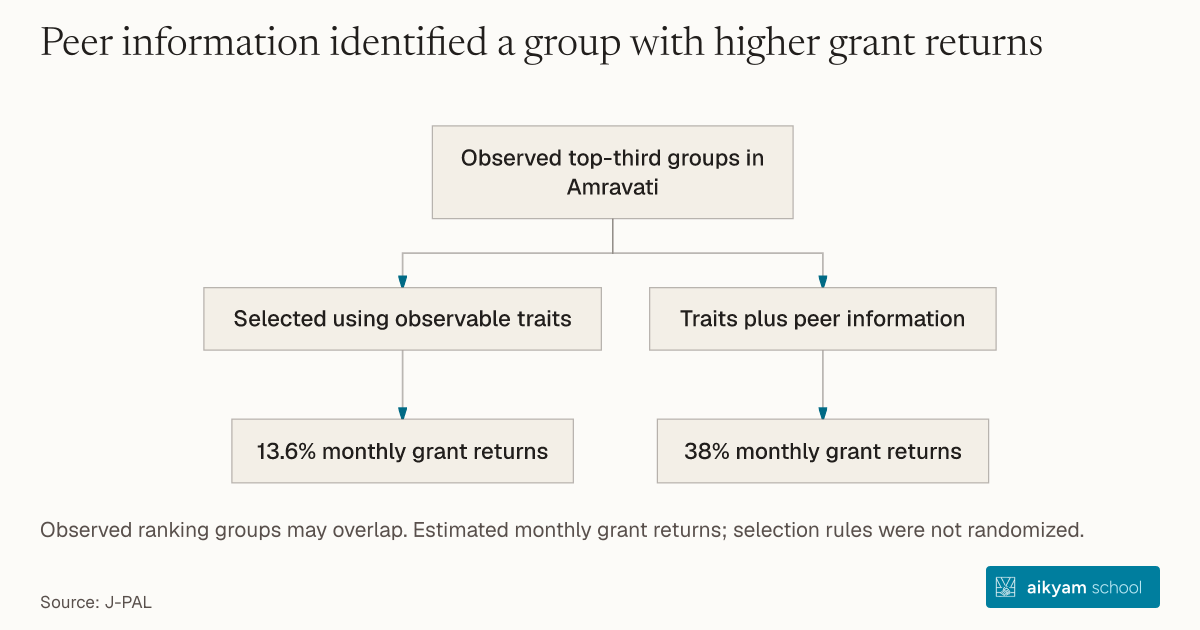
Observed top-third groups in Amravati
- Selected using observable traits
- 13.6% monthly grant returns
- Traits plus peer information
- 38% monthly grant returns
Estimated returns for top-third groups selected by two ranking rules. The groups may overlap; this is not a randomized comparison of targeting policies.
See source →Research question
Lenders traditionally rely on easily observable demographic characteristics, such as owner gender, education, age, and household size, to predict business success, but these metrics miss unobservable entrepreneurial capability. Evaluating whether combining hard demographic data with soft community intelligence yields superior predictive accuracy is critical for optimizing credit placement.
Participants
1,345 households across nine peri-urban neighborhoods organized into 274 peer groups of five in Amravati, Maharashtra, India.
Study Design
Randomized evaluation comparing monthly return on cash grants (US$100) for microentrepreneurs selected via observable traits alone versus a hybrid model combining observable traits and community peer information.
Results
Microentrepreneurs ranked in the top third based on observable traits alone achieved monthly returns of 13.6 percent, whereas those selected using both observable traits and community peer information achieved monthly returns of 38 percent.
Takeaway
Combine observable demographic data with peer-ranking scores when scoring microentrepreneur loan applications to maximize capital returns.