In Simple Words
Think of starting a business like buying a pass to an amusement park. If the pass costs a full month's income and requires filling out dozens of complex legal forms, vendors will set up outside the park gate illegally. This policy replaces the expensive gate fee with a discounted, single-click monthly pass that lowers the cost barrier so small vendors can sell inside legally.
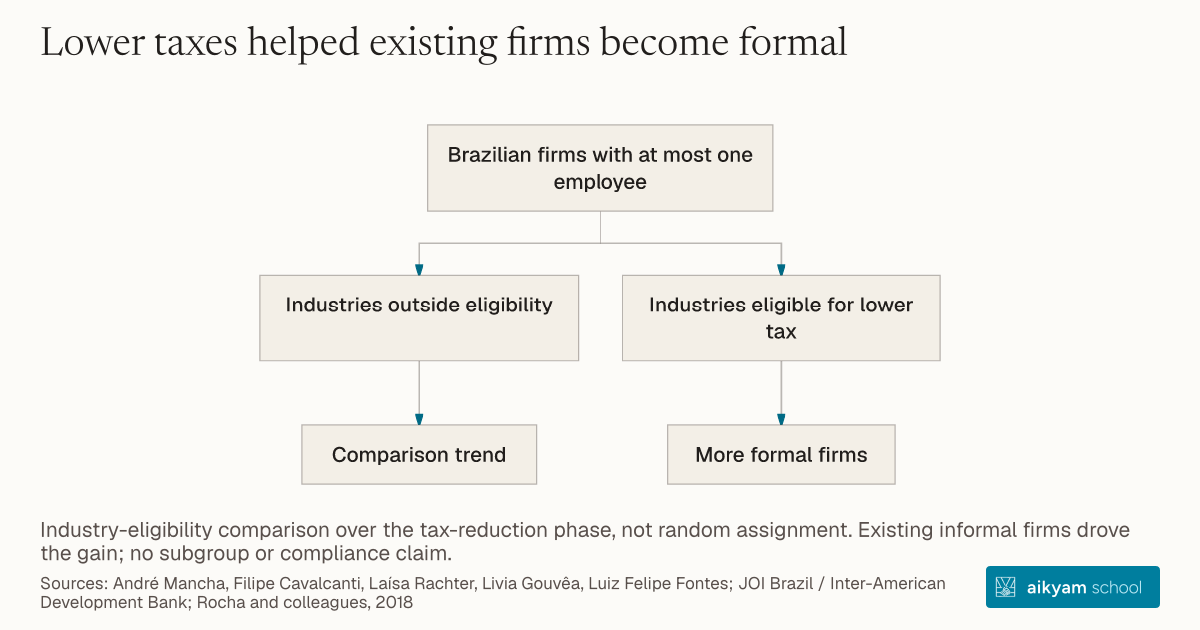
Brazilian firms with at most one employee
- Industries outside eligibility
- Comparison trend
- Industries eligible for lower tax
- More formal firms
Industry-eligibility comparison over the tax-reduction phase, not random assignment. Existing informal firms drove the gain; no subgroup or compliance claim.
See source →Study conditions — Rocha and colleagues, 2018 ↗Research question
High administrative registration costs and heavy tax burdens discourage micro-entrepreneurs from entering the formal sector, leaving workers without social protection and depressing government revenues.
Participants
Micro-entrepreneurs in Brazil with no more than one employee tracked from 2009 to 2015, and tax compliance data tracked across Brazilian Revenue Service records from 2018 to 2020.
Study Design
Quasi-experimental impact evaluation and observational administrative data analysis.
Results
The program increased business formalization between 2009 and 2015 without causing formal salaried workers to shift into micro-entrepreneurship, but generated average monthly tax default rates between 49% and 51% from 2018 to 2020.
Takeaway
Implement simplified single-tax registration regimes with reduced social security contribution rates for self-employed entrepreneurs to lower formalization barriers.
Source and citation
See source →Evidence in Labor Market Policies and Implications for Brazil: Informality
Copyright © 2025 Inter-American Development Bank.
Full source notice
Copyright © 2025 Inter-American Development Bank ("IDB"). This work is subject to a Creative Commons license CC BY 3.0 IGO (https://creativecommons.org/licenses/by/3.0/igo/legalcode). The terms and conditions indicated in the URL link must be met and the respective recognition must be granted to the IDB. Further to section 8 of the above license, any mediation relating to disputes arising under such license shall be conducted in accordance with the WIPO Mediation Rules. Any dispute related to the use of the works of the IDB that cannot be settled amicably shall be submitted to arbitration pursuant to the United Nations Commission on International Trade Law (UNCITRAL) rules. The use of the IDB's name for any purpose other than for attribution, and the use of IDB's logo shall be subject to a separate written license agreement between the IDB and the user and is not authorized as part of this license. Note that the URL link includes terms and conditions that are an integral part of this license.