In Simple Words
Giving a high-end kitchen setup to a group of people will not help everyone equally; professional chefs will double their output, whereas people who do not cook or lack time will see no benefit at all.
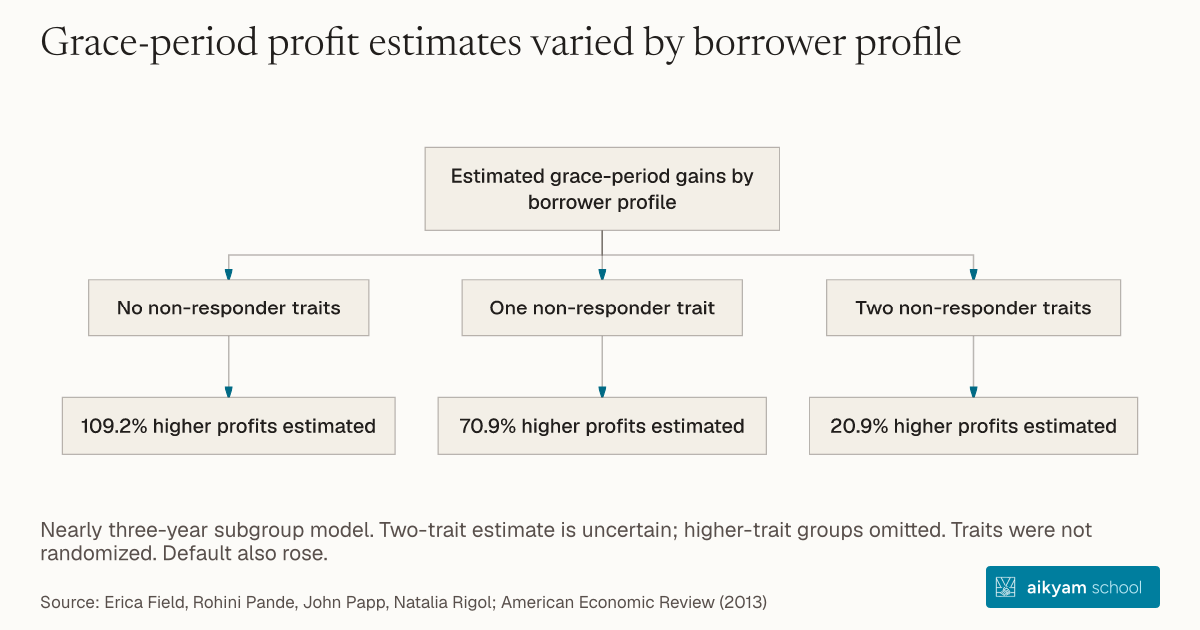
Estimated grace-period gains by borrower profile
- No non-responder traits
- 109.2% higher profits estimated
- One non-responder trait
- 70.9% higher profits estimated
- Two non-responder traits
- 20.9% higher profits estimated
Nearly three-year subgroup model. Two-trait estimate is uncertain; higher-trait groups omitted. Traits were not randomized. Default also rose.
See source →Research question
Microfinance contract flexibility does not produce uniform gains across all clients, making it necessary to evaluate composite borrower characteristics to prevent misallocating grace period loans to non-responsive entrepreneurs.
Participants
N = 752 female microfinance borrowers in urban Kolkata, India.
Study Design
OLS regression analyzing weekly profit gains three years post-disbursement interacted with a composite index (0 to 4 traits) of non-responder characteristics.
Results
Grace period treatment increases profits by 109.2% for borrowers with 0 non-responder traits (10% of sample), 70.9% for borrowers with 1 trait (36% of sample), 20.9% for borrowers with 2 traits (35% of sample), and has no significant effect for borrowers with 3 or more traits (19% of sample).
Takeaway
Deploy composite diagnostic screening tools during MFI intake to target flexible repayment contracts to borrowers possessing zero or one non-responder trait.