In Simple Words
When a parent works in a distant city and sends money home for school fees, they cannot easily verify if the money was spent on tuition or daily entertainment. Providing training or joint management tools to both the sender and receiver aligns their goals like a shared online bank account statement.
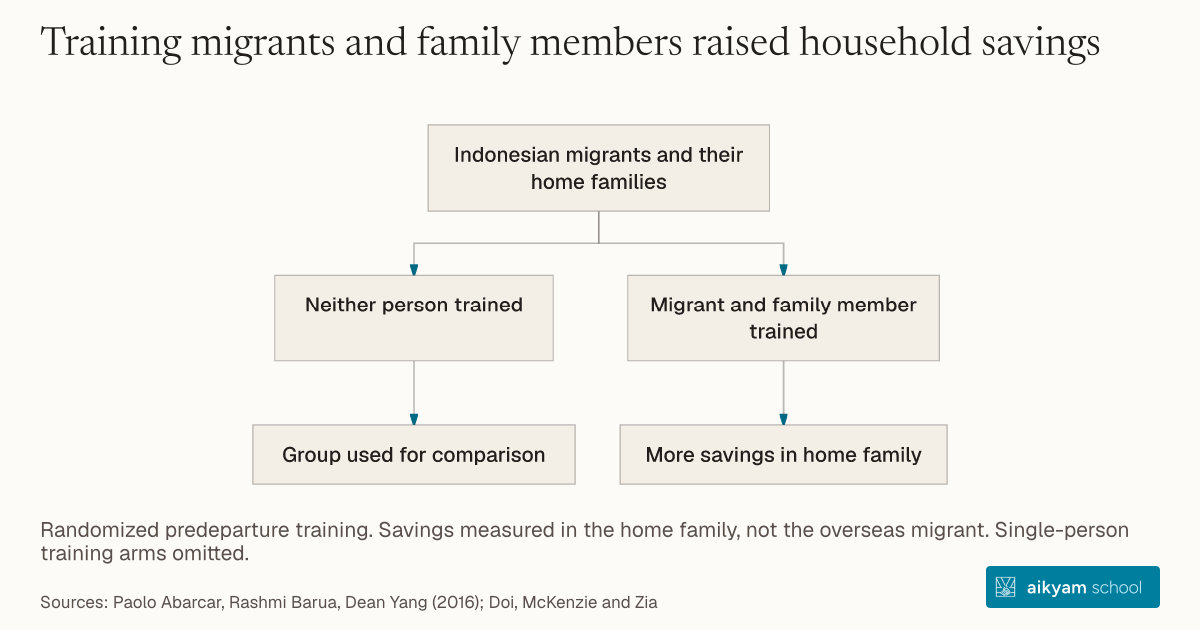
Indonesian migrants and their home families
- Neither person trained
- Group used for comparison
- Migrant and family member trained
- More savings in home family
Randomized predeparture training. Savings measured in the home family, not the overseas migrant. Single-person training arms omitted.
See source →Study conditions — Doi, McKenzie and Zia ↗Research question
Geographic separation between overseas workers and origin-country household members creates information asymmetries regarding remittance usage, leading to misaligned financial goals and sub-optimal household savings.
Participants
Review of randomized field evaluations among transnational households across developing country migration corridors (including Indonesia, Qatar, and El Salvador).
Study Design
Randomized experimental studies evaluating joint versus individual financial education and financial control mechanisms.
Results
Joint financial education for migrants and home-country recipients raises total savings and remittances while boosting joint decision-making, whereas isolated individual training yields muted impacts on financial decision-making.
Takeaway
Require joint participation of both overseas migrants and home-country decision-makers when implementing financial education or remittance-channeling initiatives.