In Simple Words
Imagine a bank offering loans to farmers but requiring them to pay back a chunk of cash every three days. Farmers who could buy fruit trees that yield huge harvests in six months are forced instead to grow low-yield radishes that ripen every three days just to meet the bank's schedule, leaving the town with much less food overall.
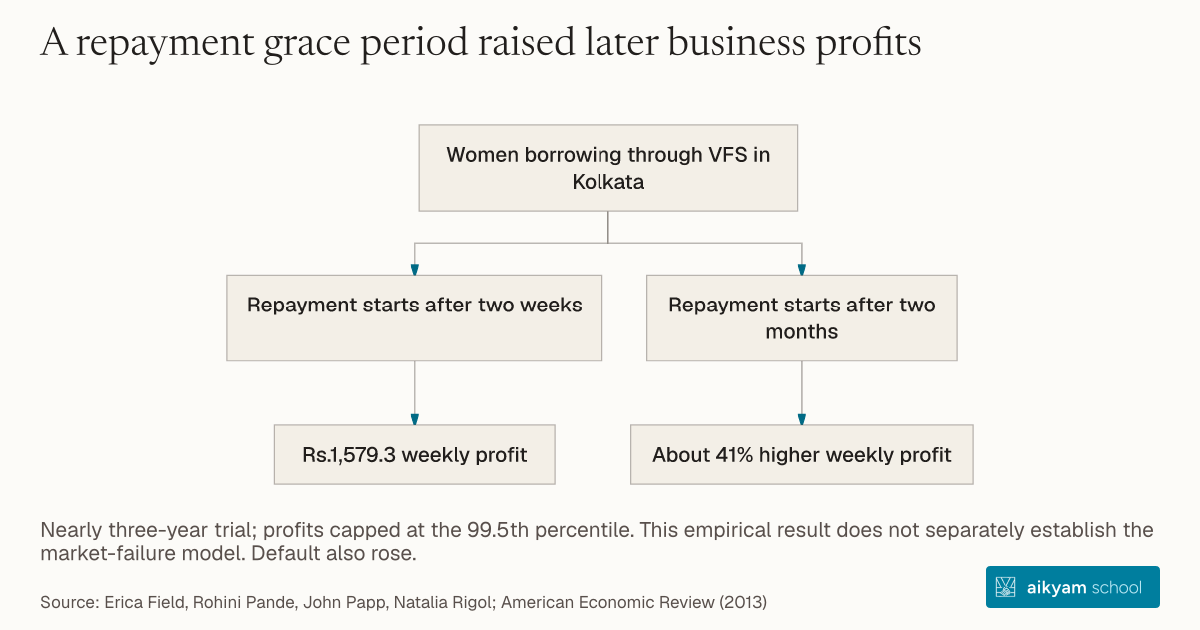
Women borrowing through VFS in Kolkata
- Repayment starts after two weeks
- Rs.1,579.3 weekly profit
- Repayment starts after two months
- About 41% higher weekly profit
Nearly three-year trial; profits capped at the 99.5th percentile. This empirical result does not separately establish the market-failure model. Default also rose.
See source →Research question
When credit market institutions prioritize contract structures that minimize default risk, they unintentionally impose restrictions that prevent poor entrepreneurs from funding high-return, illiquid projects, generating widespread underinvestment.
Participants
Theoretical synthesis and profit calibration based on 845 microfinance borrowers in Kolkata, India.
Study Design
Market failure calibration model linking lender contract choice to entrepreneurial investment distortions.
Results
Standard rigid microfinance contracts achieve high repayment rates (over 95%) but induce underinvestment by constraining borrowers to low-yielding liquid projects, forfeiting an average 41.0% increase in long-run weekly profits (Rs 640.9 top-coded).
Takeaway
Design credit policies that evaluate the social cost of entrepreneurial underinvestment alongside lender default risk when establishing lending guidelines.