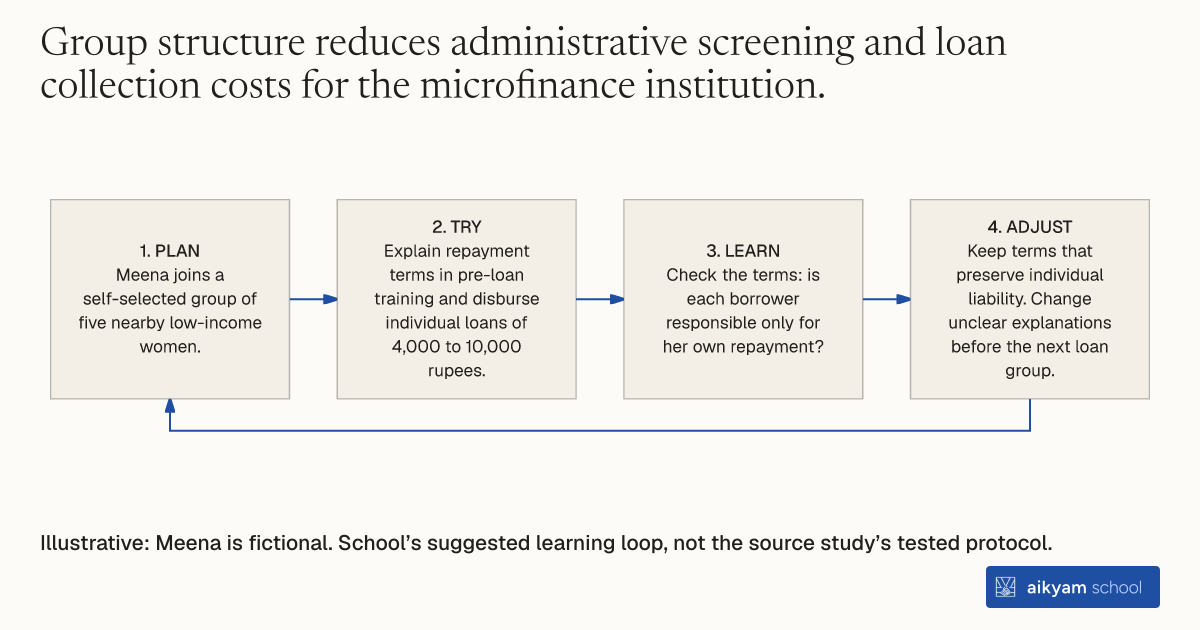
Try, learn and adjust
Check individual liability is clear before lending
- Plan: Meena joins a self-selected group of five nearby low-income women.
- Try: Explain repayment terms in pre-loan training and disburse individual loans of 4,000 to 10,000 rupees.
- Learn: Check the terms: is each borrower responsible only for her own repayment?
- Adjust: Keep terms that preserve individual liability. Change unclear explanations before the next loan group.
Illustrative: Meena is fictional. School’s suggested learning loop, not the source study’s tested protocol.
See source →Observe loan amounts and individual repayment terms; no member guarantees another’s default. School suggests this learning loop; it is not the source’s tested procedure.
How
When to use
Low-income female entrepreneurs in dense urban neighborhoods need microcredit to fund enterprise activities. Lenders want to reduce administrative costs without holding group members financially liable for each other's default. Forming self-selected borrower groups under individual liability creates social cohesion while preserving individual financial responsibility.
Form five-member borrower groups of low-income women to disburse individual microfinance loans without joint liability guarantees.
- Recruit low-income female business owners residing within close geographical proximity in urban neighborhoods.
- Form self-selected five-member client groups during community outreach meetings.
- Conduct pre-loan training sessions with each five-member group to explain repayment terms and schedule.
- Disburse individual loans between 4,000 and 10,000 rupees directly to each group member.
- Require individual repayment liability where no group member is legally or financially responsible for another member's default.
Why it works
Individual liability prevents peer pressure from forcing risk-averse group members to stop ambitious peers from making high-return investments.
Example
Village Financial Services formed 169 five-member groups comprising 845 female borrowers across 10 branch areas in Kolkata. Group members received individual loans of 4,000 to 10,000 rupees without joint liability, allowing individual entrepreneurs to select distinct business investment strategies.
About the study
Participants
845 low-income female microfinance clients in 169 five-member loan groups in Kolkata, India.
Study Design
Field randomized controlled trial assigning 169 five-member groups to regular or grace period debt contracts under individual liability.
Results
Disbursing individual liability loans to 169 five-member groups enabled 845 female borrowers to receive average loans of 4,000 to 10,000 rupees, yielding overall 3-year weekly business profit increases of 41.0 percent in grace period groups compared to regular groups.