In Simple Words
Imagine buying a lottery ticket that costs $1, but pays out $1,000 if a major storm hits. Paying $1 during normal weather is so cheap that it does not change weekly spending or force extra work hours to make up for the cost. However, on storm days when the ticket pays out $1,000, a sudden cash injection allows the holder to take time off work. The tiny upfront cost causes no noticeable disruption in normal times, but the large payout creates a dramatic change in labor behavior during emergency times.
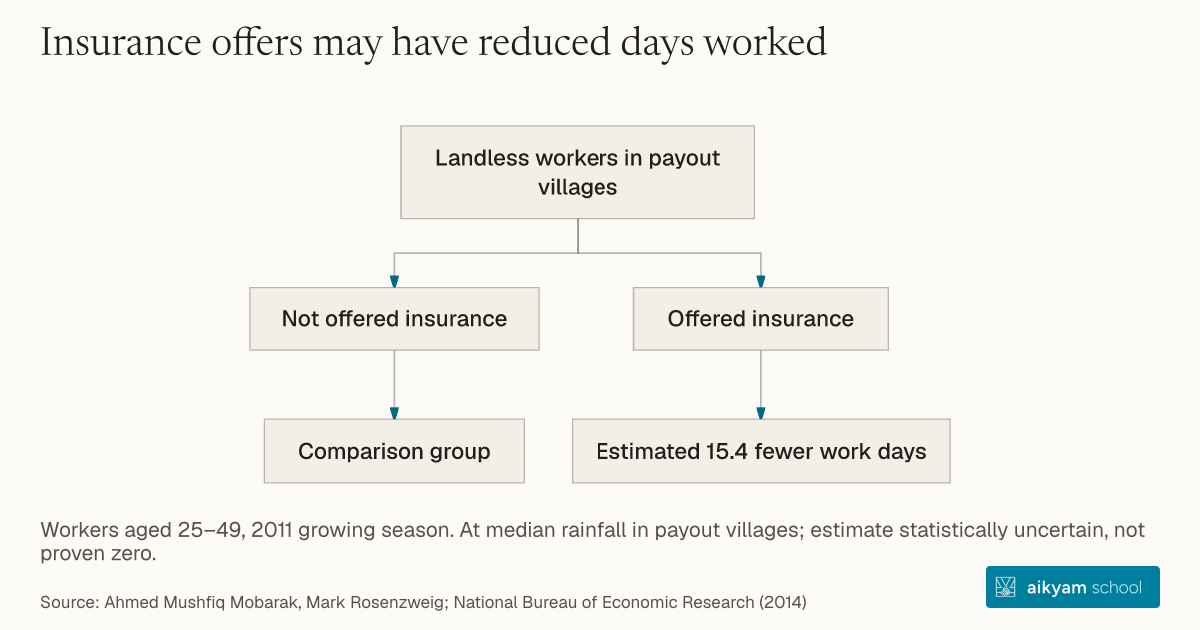
Landless workers in payout villages
- Not offered insurance
- Comparison group
- Offered insurance
- Estimated 15.4 fewer work days
Workers aged 25–49, 2011 growing season. At median rainfall in payout villages; estimate statistically uncertain, not proven zero.
See source →Research question
Microinsurance contracts require upfront premium payments that could theoretically depress household wealth in non-payout years, potentially altering labor supply decisions. Heavily subsidizing insurance premiums ensures high adoption while minimizing negative wealth effects in normal years, creating a sharp asymmetric positive wealth shock only during indemnified shock years.
Participants
4,667 households across 42 treatment villages in India receiving subsidized insurance offers at average price Rs. 145 (with 0% to 75% randomized discounts).
Study Design
Randomized subsidy trial embedded within rainfall index insurance marketing across payout (4 villages) and non-payout villages (38 villages).
Results
Overall insurance take-up reached 42%. In non-payout villages, labor participation differences between insured and uninsured workers were statistically zero (p > 0.10, point estimate -4.6 days), whereas in payout villages, insurance payouts (Rs. 300 to Rs. 1,200) reduced labor participation by 28.5 percentage points and days worked by 15.44 days.
Takeaway
Subsidize weather index premiums for low-income households to prevent ex-ante negative income shocks during non-trigger years while maintaining strong ex-post shock protection.
Source and citation
See source →Read alongside the research
Plain-English glossary
Original explanations, informed by the references below. Examples are illustrations, not data from the studies above. The research text stays unchanged.
- Percentage points
The difference between two percentages.
ExampleA rise from 40% to 50% is 10 percentage points. Relative to the starting value, that is a 25% increase.
Office for National Statistics · Percentages ↗Read more about percentage points →