In Simple Words
Imagine a gardener deciding between planting basic grass seed that grows under any condition or expensive exotic flowers that bloom spectacularly in sunshine but wither completely in heavy rain. Without weather insurance, the gardener plants basic grass every year to ensure at least some income. Once a financial policy guarantees a payout if it rains too much, the gardener plants the exotic flowers, unlocking huge potential profits whenever sunny weather occurs.
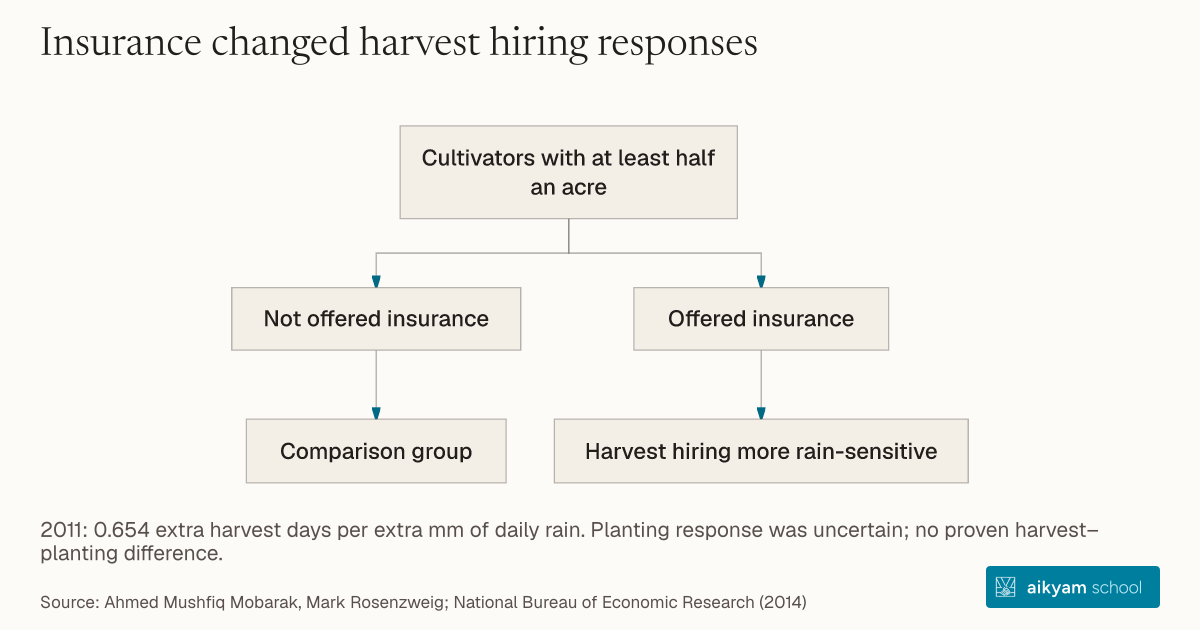
Cultivators with at least half an acre
- Not offered insurance
- Comparison group
- Offered insurance
- Harvest hiring more rain-sensitive
2011: 0.654 extra harvest days per extra mm of daily rain. Planting response was uncertain; no proven harvest–planting difference.
See source →Research question
Uninsured agricultural producers face downside income risk during unfavorable weather, forcing them to underinvest in high-yield inputs (such as specialized fertilizers and high-yield seed varieties) that depend on favorable rainfall. Removing downside financial risk through weather index insurance induces producers to shift ex-ante stage-1 input choices toward technology that maximizes productivity during good rainfall states.
Participants
1,585 cultivating households owning >0.5 acres of land across 42 sample villages in rural India.
Study Design
Theoretical stage-1 input optimization model tested empirically via harvest labor demand regressions across rainfall realizations.
Results
Offering index insurance induced cultivators to increase harvest labor demand by 0.654 days per mm/day of excess rainfall (t = 2.39), representing a 22% relative increase in labor demand sensitivity under favorable rainfall conditions.
Takeaway
Combine weather insurance products with agricultural extension services to encourage farmers to adopt weather-sensitive, high-yield input bundles.