Try, learn and adjust
Check insurance delivery through trusted peers
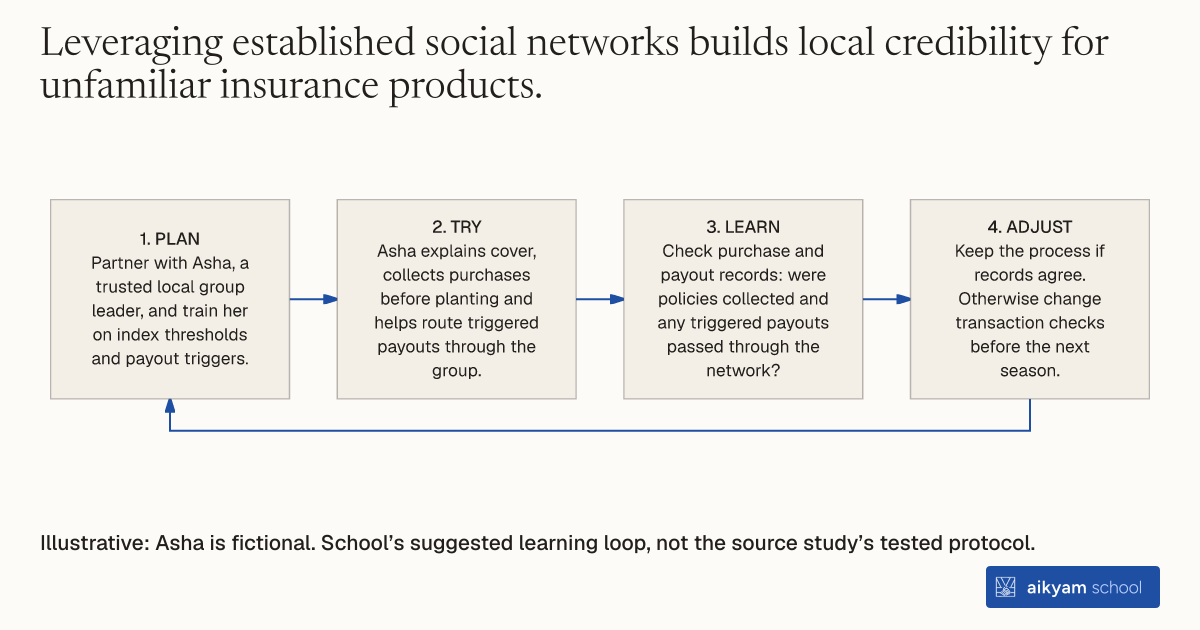
- Plan: Partner with Asha, a trusted local group leader, and train her on index thresholds and payout triggers.
- Try: Asha explains cover, collects purchases before planting and helps route triggered payouts through the group.
- Learn: Check purchase and payout records: were policies collected and any triggered payouts passed through the network?
- Adjust: Keep the process if records agree. Otherwise change transaction checks before the next season.
Illustrative: Asha is fictional. School’s suggested learning loop, not the source study’s tested protocol.
See source →School’s suggested, untested learning loop. Observe policy purchases and triggered payouts through peer networks.
How
When to use
Smallholder farmers often distrust commercial insurance companies that are unfamiliar or located outside their local communities. This lack of institutional trust reduces farmer willingness to buy complex weather index insurance. Distributing insurance through trusted local peer groups or informal community agents helps overcome institutional distrust.
Distribute weather index insurance to smallholder farmers through trusted peer groups or informal local agents to build product confidence.
- Insurance providers partner with well-known local peer groups or community intermediaries in agricultural regions.
- Program managers train informal group leaders on parametric index thresholds and payout triggers.
- Peer group leaders present the insurance product structures to neighboring farmers during local meetings.
- Informal agents collect policy purchases from participating group members before the planting season begins.
- Insurers distribute payouts through peer group networks whenever local weather station metrics trigger claims.
Why it works
Partnering with peer group leaders reduces learning barriers and boosts overall perception of product safety.
Example
Commercial insurers offered rainfall insurance through informal insurance groups and local peer networks to smallholder farmers in Ethiopia. Distributing products via trusted local intermediaries increased farmer willingness to purchase rainfall insurance.